Renovation vs. Repair: How the IRS Treats Your Spending Differently
Misclassifying a repair as a renovation — or vice versa — can cost independent landlords thousands in taxes. Here's exactly how the IRS draws the line.
In 2023, the IRS audited approximately 0.44% of all individual tax returns — but rental property owners face significantly elevated scrutiny. Why? Because rental real estate is one of the most audit-prone categories in the tax code, and one of the most common triggers is the misclassification of property expenditures. Specifically, calling a capital improvement a 'repair' to deduct it immediately, or failing to recognize when a repair has crossed into improvement territory. The financial stakes are real: the difference between an immediate deduction and a 27.5-year depreciation schedule on a $15,000 project is over $10,000 in deferred taxes in the first year alone. If you self-manage rental property, understanding how the IRS distinguishes renovations from repairs isn't optional — it's one of the highest-leverage tax strategies available to you.
This distinction has tripped up landlords for decades, but the IRS actually codified it in a cleaner way than most people realize. In 2013, the IRS issued final Tangible Property Regulations — often called the 'repair regulations' — which replaced a murky patchwork of case law with a more structured framework. Those rules, still in full effect today, give independent landlords a genuine roadmap for categorizing spending. The challenge is that most landlords never learned the framework. They guess, they ask their cousin, or they hand everything to an accountant once a year and hope for the best. This article will fix that.
The Core Distinction: Deduct Now vs. Depreciate Over Time
At its most basic, the IRS splits property expenditures into two buckets. Repairs and maintenance expenses are deducted in the year you pay them, reducing your taxable rental income dollar-for-dollar in that tax year. Capital improvements must be capitalized — meaning added to the property's cost basis — and then depreciated over the IRS-prescribed useful life of the asset. For residential rental property, that's 27.5 years under the Modified Accelerated Cost Recovery System (MACRS). For certain personal property components like appliances or carpeting, shorter depreciation schedules of 5 or 7 years apply. The bottom line: a repair gives you an immediate tax benefit, while an improvement stretches that benefit across decades.
Quick math: A $12,000 bathroom gut-renovation capitalized over 27.5 years yields roughly $436 in depreciation per year. That same $12,000 classified as a deductible repair would reduce your taxable income by the full $12,000 in year one — potentially saving $2,640–$4,440 in federal taxes depending on your bracket.
How the IRS Defines a Repair
According to IRS Publication 527 and the Tangible Property Regulations under Treasury Regulation §1.162-4, a repair is an expenditure that keeps your property in its ordinarily efficient operating condition without adding value, extending useful life, or adapting it to a new use. Repairs are routine, reactive, and restorative. They fix what's broken or worn, returning it to its prior functional state — nothing more.
Common Examples of Deductible Repairs
- Fixing a leaky faucet or replacing a worn-out faucet washer
- Patching a small section of drywall after tenant damage
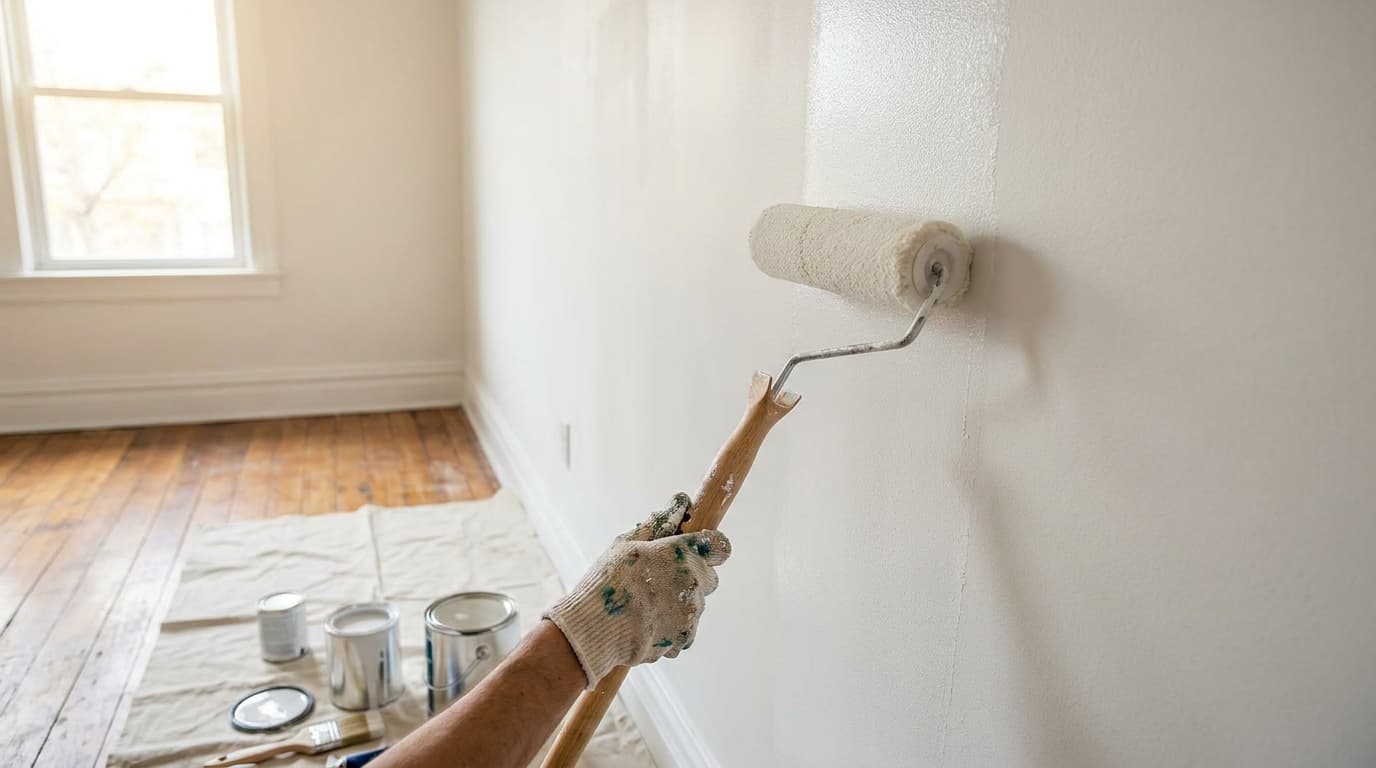
- Repainting interior walls between tenants using the same color/quality paint
- Replacing a broken window pane (single pane, like-for-like replacement)
- Fixing a stuck or broken door lock
- Unclogging and snaking a drain
- Replacing a handful of damaged shingles after a storm
- Servicing the HVAC system (filter replacement, refrigerant recharge, tune-up)
- Repairing a section of damaged hardwood flooring with matching boards
- Fixing a tripped circuit breaker or replacing a single faulty outlet
Notice the pattern: these activities return something to working order. They don't make the property materially better, extend its life significantly, or change how it's used. They restore the status quo.
How the IRS Defines a Capital Improvement
The IRS uses a three-part test under the Tangible Property Regulations to determine whether an expenditure must be capitalized. If the work results in a Betterment, a Restoration, or an Adaptation, it's a capital improvement — even if it feels like a repair to you. This is commonly called the 'BAR' test, and understanding each prong is essential.
The BAR Test: Betterment, Adaptation, Restoration
- 1Betterment: The expenditure materially increases the property's value, productivity, or quality. Installing a new HVAC system that's significantly more efficient than the original, or upgrading from laminate countertops to quartz, qualifies as a betterment — the property is objectively better than before.
- 2Adaptation: The expenditure adapts the unit or building to a new or different use. Converting a garage into a rentable studio apartment, or turning a single-family home into a duplex, clearly adapts the property. Even converting a storage room into a laundry room for tenants can cross this line.
- 3Restoration: The expenditure restores the property to like-new condition, rebuilds it after the end of its depreciable life, or replaces a major component. A full roof replacement (not a patch), replacing all windows throughout the building, or installing an entirely new plumbing system qualifies as restoration.
Common Examples of Capital Improvements
- Full kitchen gut renovation — new cabinets, countertops, appliances, and flooring
- Complete bathroom remodel — new tile, vanity, fixtures, tub/shower unit
- Roof replacement (full tear-off and re-roof)
- Adding a deck, patio, or garage
- Installing central air conditioning where none existed before
- Replacing the entire HVAC system with a new one
- Replacing all windows throughout the property
- Installing new hardwood floors throughout (replacing carpet entirely)
- Converting a basement into a finished living space
- Installing a new water heater (full replacement, not repair)
Important: The IRS looks at the 'unit of property' when applying the BAR test. For a building, the unit of property includes structural components grouped into specific systems — HVAC, plumbing, electrical, roofing, and so on. Work that affects an entire system is more likely to be a capital improvement than work on a single component within that system.
The Gray Zone: Where Landlords Get It Wrong
The IRS framework is clear in theory, but real-world spending is messy. The most common mistakes independent landlords make aren't blatant fraud — they're honest misclassifications in genuinely ambiguous situations. Here are the scenarios that cause the most confusion.
Replacement vs. Repair: The 'Like-for-Like' Trap
Many landlords assume that replacing something broken with an identical (or similar) item is always a repair. Not quite. The IRS considers whether you're replacing a major component of a system or the entire system itself. Replacing a burner on a gas stove? Repair. Replacing the entire stove? That's replacing a unit of property, and depending on its cost and context, it may need to be capitalized as a new appliance — though the de minimis safe harbor (discussed below) may save you here. Replacing one section of pipe? Repair. Replacing the entire plumbing system? Capital improvement.
Cosmetic vs. Functional Upgrades
Repainting your rental between tenants is a repair. But what if you're not just repainting — you're also replacing all the interior doors, upgrading to premium trim, and installing new light fixtures throughout? Each item might be small, but the aggregate project is improving the property. The IRS can and does look at the totality of work performed in close proximity to determine whether what's being called a 'maintenance project' is actually a capital improvement in disguise. Grouping work by project intent matters.
Emergency Work After Casualty Events
If a pipe bursts and floods your rental, the remediation work feels like a repair — you're just fixing damage. But here's the IRS wrinkle: if the insurance claim or repair scope results in work that restores the unit to better-than-original condition, the improvement portion must be capitalized. Landlords who gut a flooded unit and upgrade finishes in the process cannot deduct the entire cost as a repair, even if the flood caused the project.
Safe Harbors That Can Save You Money
The 2013 Tangible Property Regulations didn't just define the problem — they also introduced several IRS-sanctioned safe harbors that allow landlords to deduct certain expenditures that might otherwise be classified as capital improvements. These are your best friends as an independent landlord.
1. The De Minimis Safe Harbor
Under IRS Rev. Proc. 2015-20, taxpayers without an Applicable Financial Statement (AFS) — which includes virtually all individual landlords — can elect to expense items costing $2,500 or less per item or invoice. This means if you replace a water heater for $1,800, buy a new refrigerator for $900, or purchase a new dishwasher for $600, you can deduct these immediately rather than depreciating them, as long as you elect this safe harbor on your tax return. The election must be made annually on your tax return. You don't have to ask permission — you simply include a statement with your return indicating you're using the de minimis safe harbor.
2. The Safe Harbor for Small Taxpayers
This safe harbor is specifically designed for independent landlords. If your rental building's unadjusted basis is $1 million or less, and your gross receipts are under $10 million, you can elect to deduct the lesser of (a) $10,000 or (b) 2% of the building's unadjusted basis per year in repair and maintenance costs without capitalizing them — even if those expenditures would otherwise qualify as improvements. For a property with an unadjusted basis of $200,000, that's up to $4,000 per year in deductible maintenance and improvement costs. This is a significant benefit that many self-managing landlords never use because they don't know it exists.
3. Routine Maintenance Safe Harbor
Activities you reasonably expect to perform more than once during the building's depreciable life (27.5 years) to maintain the property in its ordinarily efficient operating condition can be deducted as routine maintenance — even if they technically constitute a restoration under BAR. Painting, cleaning, servicing HVAC systems, and similar recurring activities typically qualify. The key test: would a reasonable property owner expect to do this more than once over 27.5 years? If yes, it's likely deductible as routine maintenance.
Bonus Depreciation and Section 179: When Faster is Better
Even when an expenditure must be capitalized, there are mechanisms to accelerate deductions. Bonus depreciation under the Tax Cuts and Jobs Act allowed 100% first-year deduction for qualifying property placed in service from 2017–2022. As of 2024, bonus depreciation has phased down to 60% and continues declining 20% per year under current law (40% in 2025, 20% in 2026, then zero in 2027 unless Congress acts). Section 179 expensing is another option, though it comes with limitations for rental property — it generally cannot be used to create a loss from rental activity.
Cost segregation studies are a more advanced strategy that independent landlords with larger portfolios or recent acquisitions should know about. A cost segregation study performed by an engineering firm reclassifies components of your building — flooring, cabinetry, certain electrical — from 27.5-year property to 5- or 7-year property, dramatically accelerating depreciation. The IRS fully supports cost segregation when done properly, and studies routinely generate $20,000–$100,000+ in accelerated deductions for mid-sized properties. For landlords with four or more units, the ROI on a cost segregation study is often compelling.
Pro Tip: If you've owned rental property for years and never done a cost segregation study, you can perform a 'look-back' study under Rev. Proc. 2002-9 and catch up on missed depreciation without amending prior returns — using Form 3115 instead. Talk to a CPA who specializes in real estate.
Documentation: The Part Most Landlords Skip
Winning an IRS audit isn't just about having the right classification — it's about having the paperwork to prove it. The IRS requires landlords to substantiate deductions with contemporaneous records. That means receipts, invoices, contractor bids, before-and-after photos, and a paper trail connecting each expense to a specific property and date. According to a 2022 NFIB survey, nearly 40% of small business owners — including rental property owners — admit they don't keep adequate documentation for tax purposes. That's a massive exposure.
What Good Documentation Looks Like
- Invoices from contractors or vendors showing the specific work performed, date, property address, and amount paid
- Receipts for materials purchased at hardware stores with itemized line items
- Bank or credit card statements showing payment dates and amounts
- Emails or text messages with contractors describing the scope of work
- Photos dated before, during, and after the work was performed
- A log or spreadsheet categorizing each expense by property, date, type (repair vs. improvement), and deduction treatment
- Your written rationale for classification when an expenditure is in a gray area
This is where technology makes a real difference for independent landlords. VerticalRent's AI expense categorizer automatically tags and categorizes property-related expenses as they're entered, flagging items that may need additional documentation or that cross classification thresholds. Instead of scrambling in April to reconstruct a year of spending from a pile of receipts, your records are organized, categorized, and exportable year-round. That's not just a convenience — it's audit protection.
A Practical Classification Checklist for Landlords
When you're faced with a property expenditure and need to classify it, run through these questions in order. This isn't legal advice — always confirm with your CPA — but it's a solid working framework.
- 1Does the work restore something broken to its prior working condition without making it better? If yes → likely a deductible repair.
- 2Does the work result in the property being materially better, longer-lasting, or more valuable than before the work? If yes → likely a capital improvement (Betterment).
- 3Does the work adapt the property or a portion of it to a new or different use? If yes → capital improvement (Adaptation).
- 4Does the work replace a major structural component or an entire system (roof, HVAC, plumbing, electrical)? If yes → likely a capital improvement (Restoration).
- 5Does the expenditure fall under the De Minimis Safe Harbor ($2,500 or less per item/invoice)? If yes → elect the safe harbor and deduct immediately.
- 6Does the building qualify for the Small Taxpayer Safe Harbor and does the total annual maintenance spending fall within the $10,000 / 2% threshold? If yes → consider electing the safe harbor.
- 7Would a reasonable landlord expect to perform this same work again within 27.5 years as routine upkeep? If yes → consider the Routine Maintenance Safe Harbor.
- 8Have you documented everything — invoice, date, property address, scope, amount, and your classification rationale? If not → do it now, before you forget.
Real-World Scenarios: Repair or Improvement?
Scenario 1: The Flooring Dilemma
Your tenant moves out and the carpet is destroyed. You decide to replace it with luxury vinyl plank (LVP) flooring throughout the unit. This is almost certainly a capital improvement. You're not restoring a specific damaged area — you're replacing the entire floor covering system with a new product of higher quality and durability than the original carpet. The LVP will last significantly longer, and the unit's value and rental appeal have increased. Capitalize it, depreciate over 5 years (personal property), and consider whether bonus depreciation applies. If the total cost is under $2,500, you may be able to use the de minimis safe harbor.
Scenario 2: The HVAC Call
Your furnace stops heating properly. You call an HVAC technician who replaces the blower motor and heat exchanger for $1,100. This is a repair. You're replacing failed components within an existing system, restoring it to its original working condition. The system as a whole is unchanged — you're just fixing what broke. Deduct it in full in the year you pay it.
Scenario 3: The Roof Decision
After a major hailstorm, your property needs significant roof work. The contractor gives you two options: (a) replace damaged sections only for $4,200, or (b) full tear-off and re-roof for $14,500. Option A is almost certainly a repair — you're patching damaged sections, restoring the roof's prior condition. Option B is a capital improvement — you're replacing the entire roofing system. The tax treatment of these two choices is dramatically different, and it's worth factoring that into your decision-making alongside the long-term structural benefits.
Keeping It All Straight Throughout the Year
The classification decisions you make at the moment of spending — not at tax time — determine your tax outcome. Landlords who wait until April to sort through 12 months of expenses are working blind, making guesses under pressure that an organized landlord would never have to make. The solution is a system: a consistent process for capturing, categorizing, and documenting every property-related expenditure the moment it occurs.
VerticalRent's AI expense categorizer was built specifically for this workflow. As you log expenses — whether maintenance calls, vendor invoices, or material purchases — the AI suggests category classifications, flags items that may exceed de minimis thresholds, and maintains a property-by-property expense history that maps directly to your Schedule E. Frank, VerticalRent's AI assistant, can also answer classification questions in plain English, walk you through the BAR test for a specific project, or help you draft documentation language for gray-area expenditures. It's not a substitute for your CPA, but it dramatically raises the quality of the records and decisions you bring to your CPA.
The Bottom Line on Taxes and Property Spending
The IRS isn't trying to trick you — the Tangible Property Regulations are actually more landlord-friendly than the case-law patchwork they replaced. The system rewards landlords who understand the framework and use the available safe harbors intelligently. According to the National Association of Residential Property Managers, improper expense classification is consistently cited as one of the top three tax errors among self-managing landlords. The fix isn't complicated — it's education and documentation.
Know the BAR test. Use the de minimis safe harbor. Consider the small taxpayer safe harbor for your properties. Keep contemporaneous records for every expenditure. Work with a CPA who understands real estate taxation. And use tools that make documentation automatic rather than an afterthought. If you get these fundamentals right, you'll maximize your current-year deductions, avoid costly misclassifications, and walk into any audit with confidence.
Ready to stop guessing on expense classification and start managing your rentals like a pro? VerticalRent gives independent landlords AI-powered expense categorization, automated rent collection, tenant screening, and tools that keep your records audit-ready year-round — all in one platform built for self-managing landlords. Sign up free at VerticalRent.com and see why thousands of independent landlords trust VerticalRent to run their rentals smarter.
Put this into practice
VerticalRent tools related to this guide
Legal Disclaimer
VerticalRent and its authors are not attorneys, CPAs, or licensed legal or financial advisors, and nothing on this site constitutes legal, tax, or professional advice. The information in this article is provided for general educational purposes only. Landlord-tenant laws, eviction procedures, security deposit rules, and tax regulations vary significantly by state, county, and municipality — and change frequently. Nothing on this site creates an attorney-client relationship. Always consult a licensed attorney or qualified professional in your jurisdiction before taking any action based on information you read here.
Co-founded VerticalRent in 2011, growing it from nothing to 100k landlords and renters. Sold it in 2019, then re-acquired it in 2026 to make it better than ever.


